Skip to content
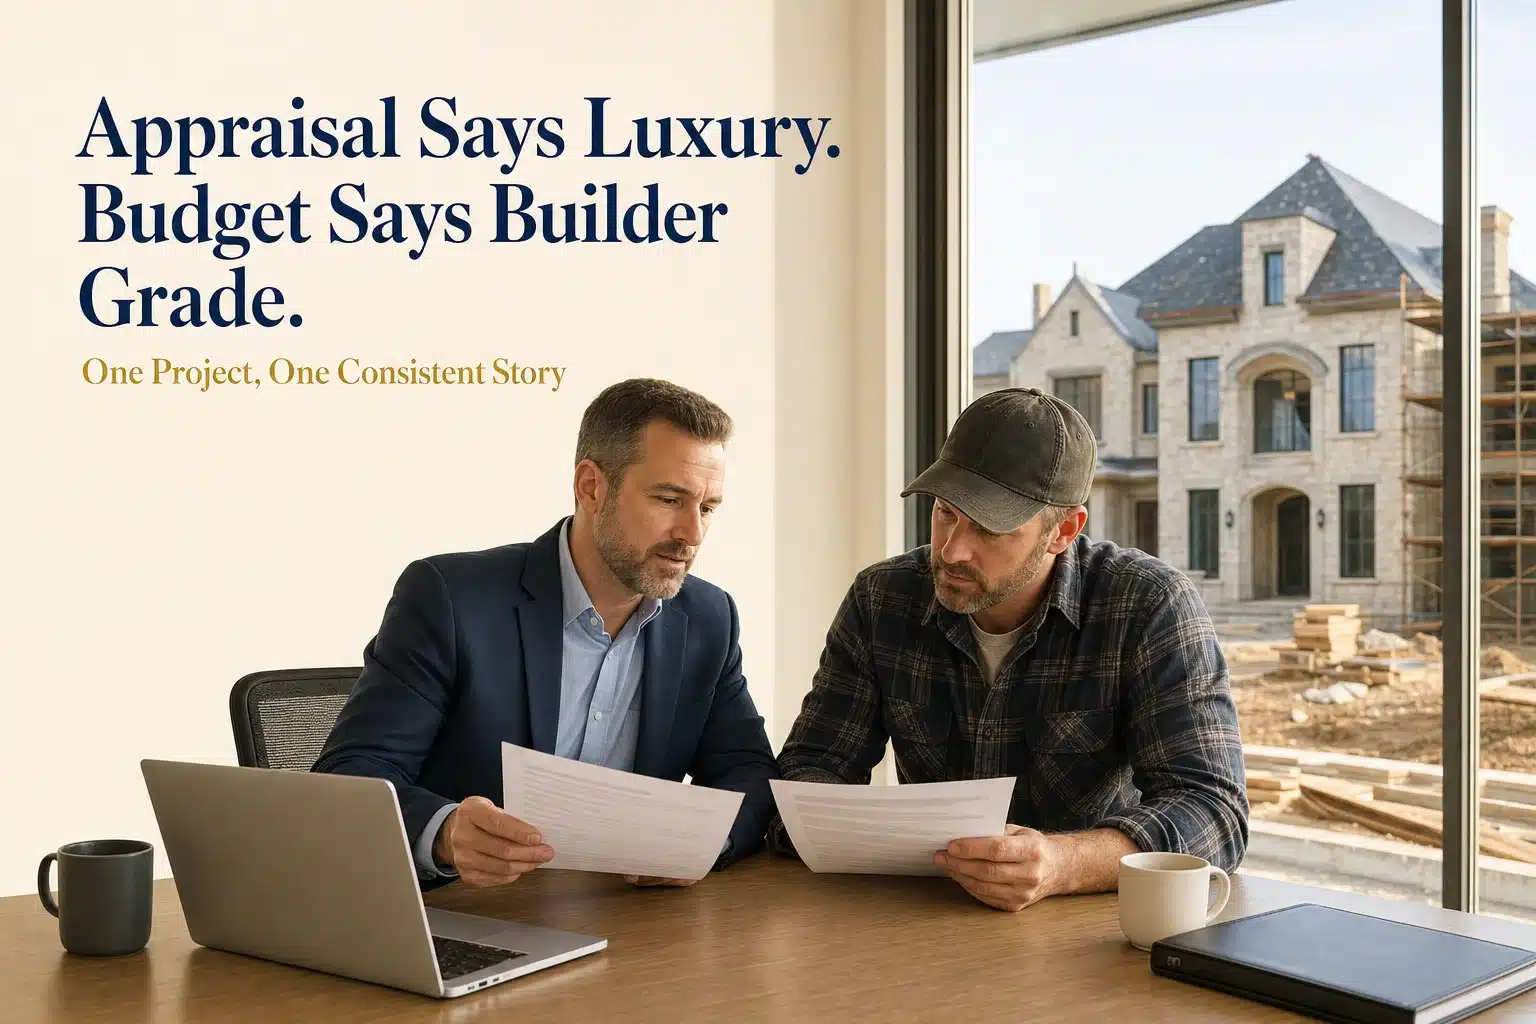
I recently looked at a construction loan where two documents told completely different stories.
The appraisal described an ultra-luxury home.
Elevator.
Rooftop terrace.
Outdoor kitchen.
High-end finishes.
Specialty features.
Even a grotto.
This wasn’t being presented as an average new-construction house with upgraded countertops and nicer appliances. The entire value conclusion was based around a very specific product: a high-end luxury residence with the finishes and amenities buyers expect at that level.
The appraisal reflected that.
The projected value was strong.
The appraiser also estimated that the home would cost somewhere close to $300 per square foot to build.
Then I opened the contractor’s line-item construction budget.
And that document told a completely different story.
A lot of the line items looked much closer to builder-grade construction.
The total budget worked out somewhere in the mid-$100s per square foot.
So naturally I asked the question a lender is going to ask:
How are we building the house described in the appraisal with the budget shown here?
The builder had an answer.
He had decades of experience.
He had relationships with subcontractors.
He knew suppliers.
He knew the market.
He could negotiate better pricing.
He didn’t have the overhead another builder might have.
He had built enough homes to know what things actually cost.
And quite frankly, some of that may be completely true.
An experienced builder may absolutely be able to build more efficiently than the assumptions used by an appraiser.
That isn’t really the issue.
The issue is that a construction lender cannot underwrite a multimillion-dollar project based on the assumption that this particular builder must remain involved for the numbers to work.
That is where builders and lenders sometimes look at the same project from two completely different perspectives.
The Appraisal and Budget Have to Describe the Same House
This is the first problem.
If your appraisal says the completed property will be an ultra-luxury home, then your construction budget needs to support the construction of an ultra-luxury home.
Those two documents should run parallel.
The value of the property isn’t being created by square footage alone.
A 6,000-square-foot builder-grade house and a 6,000-square-foot ultra-luxury house are not necessarily the same product.
The finishes matter.
The appliances matter.
The windows matter.
The doors matter.
The millwork matters.
The flooring matters.
The mechanical systems matter.
The exterior materials matter.
The outdoor improvements matter.
And if the appraisal specifically gives value to things like an elevator, rooftop entertainment area, outdoor kitchen, pool package, grotto, specialty landscaping or custom architectural details, those features can’t disappear when we turn the page to the construction budget.
You can’t tell the appraiser:
“This house is going to have everything.”
And then tell the lender:
“Don’t worry. We can build everything for half of what the appraisal assumes.”
Maybe you can.
But the lender is going to want to understand exactly how.
The ARV Is Based on What You’re Promising to Build
The projected completed value, often called the ARV or after-repair value, is not an abstract number.
It is based on a finished product.
If the appraiser concludes that the home will be worth $4 million when complete, that conclusion is based on assumptions about what will actually be standing there when construction is finished.
If those assumptions include premium finishes and significant amenities, the lender is lending against that finished product.
That means the construction budget has to reasonably support delivery of that product.
Let’s use an exaggerated example.
Suppose an appraisal says a finished luxury home will be worth $5 million.
The appraisal assumes a custom home with imported flooring, premium windows, extensive millwork, elevator, pool, outdoor kitchen and a large landscaping package.
Then the builder submits a budget that looks like it belongs to a $2 million production home.
The lender has a problem.
If the lender accepts the high appraisal but also accepts a low budget that cannot reasonably reproduce the specifications behind that appraisal, the lender may be underwriting value that never actually gets created.
That is the disconnect.
The lender isn’t accusing the builder of lying.
The lender is asking whether the economics of the project are internally consistent.
“But I Can Build It Cheaper”
This is probably the most common argument.
And it can be a legitimate argument.
Good builders do build cheaper.
Experienced general contractors have relationships.
They know which subcontractors perform.
They know where material can be sourced.
They know where money gets wasted.
They may self-perform certain work.
They may buy materials directly.
They may have crews available at rates a replacement contractor could never obtain.
A GC who has been operating for 25 years may be able to build the exact same home substantially cheaper than someone entering the market today.
I understand that.
Most lenders understand that too.
But here is the question the lender has to ask:
What happens if you don’t finish it?
That is the part many builders don’t consider.
The Bank Has to Underwrite the House Without You
Construction lending has an uncomfortable reality built into it.
The lender has to consider the possibility that something goes wrong.
The GC gets sick.
The GC’s company fails.
A dispute breaks out between the borrower and contractor.
Subcontractors walk off the job.
A lawsuit develops.
The builder dies.
The relationship falls apart.
The contractor gets overloaded with other projects.
Or the builder simply says, “I’m done.”
Nobody wants any of those things to happen.
The lender isn’t assuming they will happen.
But underwriting exists to evaluate what happens if they do.
If construction stops halfway through and the original builder disappears, the lender may need the project finished by someone else.
Now imagine the lender calls another qualified contractor.
That contractor looks at the plans and says:
“To finish this house according to these specifications, I need another $900,000.”
But there is only $400,000 left in the construction budget.
Now what?
That is exactly the scenario a lender is trying to avoid.
The Lender Does Not Want to Become the Builder
People sometimes think a construction lender’s biggest fear is foreclosure.
On a partially completed luxury home, foreclosure may only be the beginning of the problem.
The lender doesn’t want to own a construction project.
The lender doesn’t want to hire plumbers.
The lender doesn’t want to negotiate change orders.
The lender doesn’t want to find a new framing crew.
The lender doesn’t want to figure out which Italian tile was specified for the primary bathroom.
The lender doesn’t want to manage a pool contractor.
The lender wants to lend money.
That’s it.
So the underwriting has to give the lender confidence that, even in a bad scenario, there is enough money allocated to complete the asset that supports the loan.
That is why the budget cannot depend entirely on one builder’s special relationships.
If the economics only work because one particular GC is willing to do everything at an unusually low price, the lender is effectively being held hostage by that GC.
The builder may not see it that way.
The lender absolutely does.
The Lender Needs a Replacement-Cost Safety Net
Think of the construction budget as more than a prediction.
It is also a safety net.
The lender wants reasonable assurance that if the current construction team vanished tomorrow, another competent builder could take the plans, take the remaining funds and finish the project substantially as designed.
Maybe not with the exact same efficiency.
Maybe not with the exact same subcontractor pricing.
Maybe not with the same profit margin.
But the numbers still have to work.
This is why contingency matters too.
Construction loans are not built around a fantasy where material prices never move, nothing unexpected is found on site and every subcontractor honors the original price.
There needs to be room.
The more complicated the house, the more important that becomes.
A straightforward 2,200-square-foot spec home is one thing.
A custom luxury home with specialty structural work, elevators, exterior kitchens, pools, custom glazing, rooftop terraces and unique architectural features is another.
Every unusual feature introduces another place where cost can move.
The Right Answer Isn’t Necessarily to Throw Out the Builder’s Budget
This is important.
If a builder really can deliver the project for substantially less than typical market cost, that shouldn’t automatically be ignored.
But it needs to be documented.
Show the lender why.
Get actual subcontractor bids.
Get material quotes.
Show executed contracts where possible.
Break down allowances.
Identify self-performed work.
Show where the savings are coming from.
If your electrical number is 25% below what the appraiser assumed, maybe you have a valid reason.
Show it.
If your windows are being purchased directly from a manufacturer at a negotiated builder rate, show the quote.
If your excavation company has worked with you for 15 years and has provided a firm bid, include it.
If you’re acting as your own GC and eliminating a typical 15% general contractor markup, explain that.
A lender is much more likely to accept a low number when there is evidence behind it.
“Trust me, I’ve been doing this for 30 years” may be completely sincere.
It is not an underwriting document.
Cost Per Square Foot Can Be Misleading Too
One caution here.
Cost per square foot is a useful shorthand, but it is not the entire story.
A $175-per-square-foot house is not automatically under-budget.
A $300-per-square-foot house is not automatically overpriced.
Location matters.
Finishes matter.
Site conditions matter.
Architecture matters.
The number of kitchens and bathrooms matters.
Basements matter.
Pools matter.
Elevators matter.
Complex rooflines matter.
Retaining walls matter.
Imported materials matter.
A small ultra-luxury home can actually have a higher cost per square foot than a much larger house because expensive kitchens, bathrooms and systems are being spread across fewer square feet.
So I would never reject a construction budget just because its cost-per-square-foot number is lower than an appraiser’s estimate.
I would ask a different question:
Does the detailed budget credibly deliver the house described in the appraisal?
That is the real test.
This Is Really About Protecting the Project
Builders can sometimes feel like the lender is trying to inflate their budget.
That’s usually not the goal.
A properly structured construction budget protects everybody.
It protects the lender.
It protects the investor.
It protects the builder.
And it protects the project itself.
One of the worst things that can happen is getting 70% through construction and discovering there isn’t enough money left to finish the house.
At that point everybody loses leverage.
Subcontractors know you’re stuck.
The borrower may have to inject unexpected capital.
The lender may stop draws.
The project gets delayed.
Interest continues accruing.
Carrying costs increase.
And a property that was supposed to be a profitable luxury build becomes a financial rescue operation.
A realistic budget at the beginning is far cheaper than a funding crisis near the end.
The Best Files Tell One Consistent Story
When I look at a construction loan, I want the documents to agree with each other.
The plans say one thing.
The specifications support the plans.
The appraisal values that finished product.
The construction budget shows how we are going to build that product.
The draw schedule follows the construction budget.
And the borrower’s liquidity gives us enough room to deal with normal surprises.
That is a financeable story.
The problem starts when every document describes a different project.
Luxury appraisal.
Builder-grade budget.
Aggressive timeline.
Minimal contingency.
Limited liquidity.
And then everyone wants the lender to assume nothing will go wrong.
That is not how a construction lender looks at risk.
Your Experience Still Matters
An experienced builder absolutely deserves credit for experience.
Experience lowers risk.
Relationships lower cost.
Good subcontractors lower risk.
Efficient purchasing lowers cost.
A GC who has successfully built 50 homes should not necessarily be underwritten exactly like someone building their first one.
But experience should make the numbers more credible.
It shouldn’t be used as a substitute for numbers that don’t reconcile.
The strongest builder file is not:
“I have been doing this for 30 years. Trust me.”
It is:
“I have been doing this for 30 years, and here are the bids, contracts, supplier relationships and historical jobs showing exactly why this budget works.”
That’s a completely different conversation.
The Bottom Line
If your appraisal describes a Ferrari, your construction budget can’t describe a Toyota and expect the lender not to notice.
The projected value and the cost to create that value have to make sense together.
That doesn’t mean the appraiser is always right.
It doesn’t mean the contractor is always wrong.
And it doesn’t mean every luxury home has to cost whatever generic per-square-foot figure appears in an appraisal.
It means the lender needs to be able to look at the project and say:
“If the current team performs as expected, this project works.
And if something goes wrong, we still have a reasonable path to completion.”
Because at the end of the day, the lender wants to finance your build.
They do not want to inherit it.
Planning a construction project? Run your numbers with the construction loan calculator, or start a pre-qualification and let’s look at your file together.
Building a ground-up or heavy rehab project? See VeeCasa Funding construction loans and our Builder Resources.