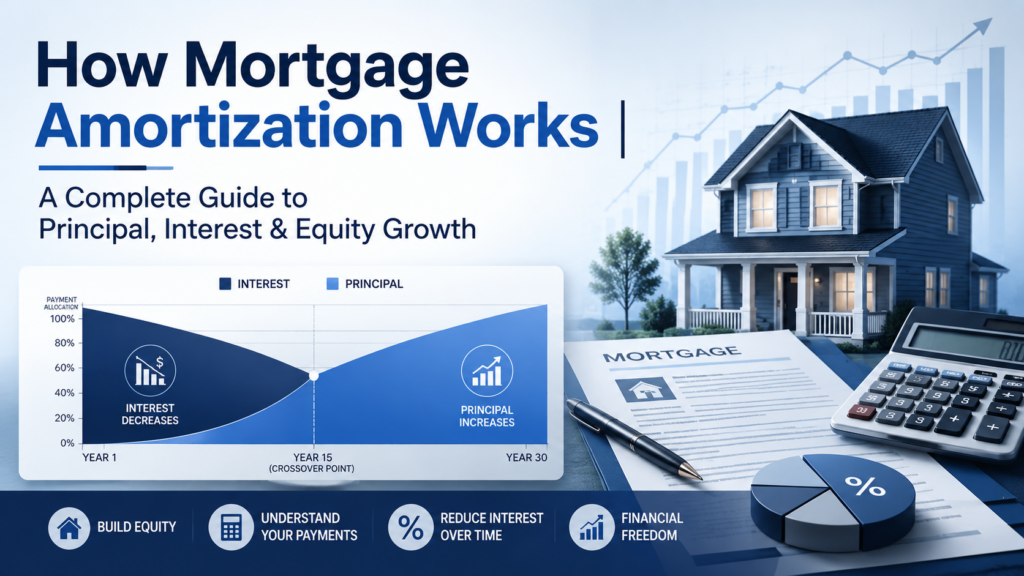
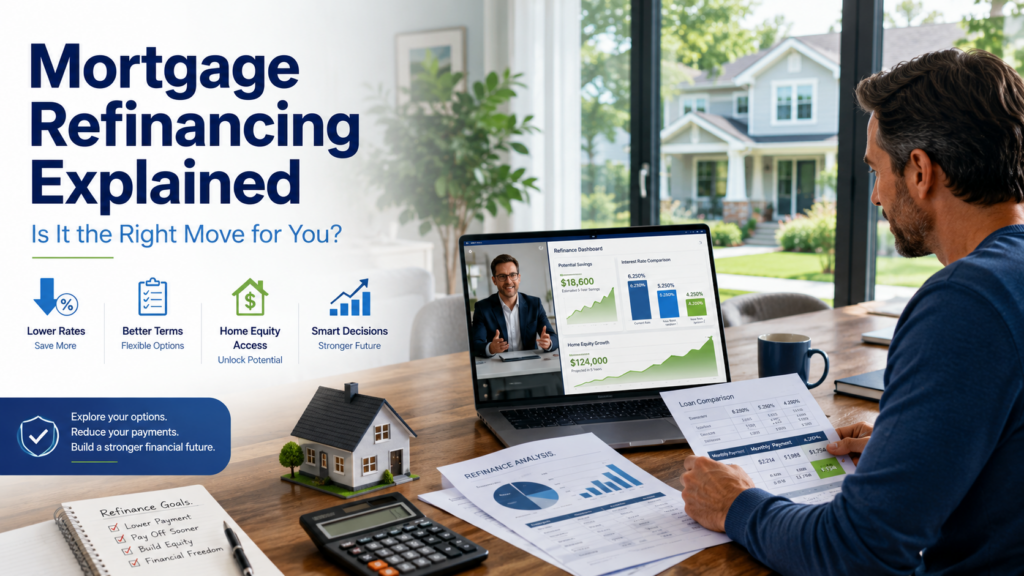
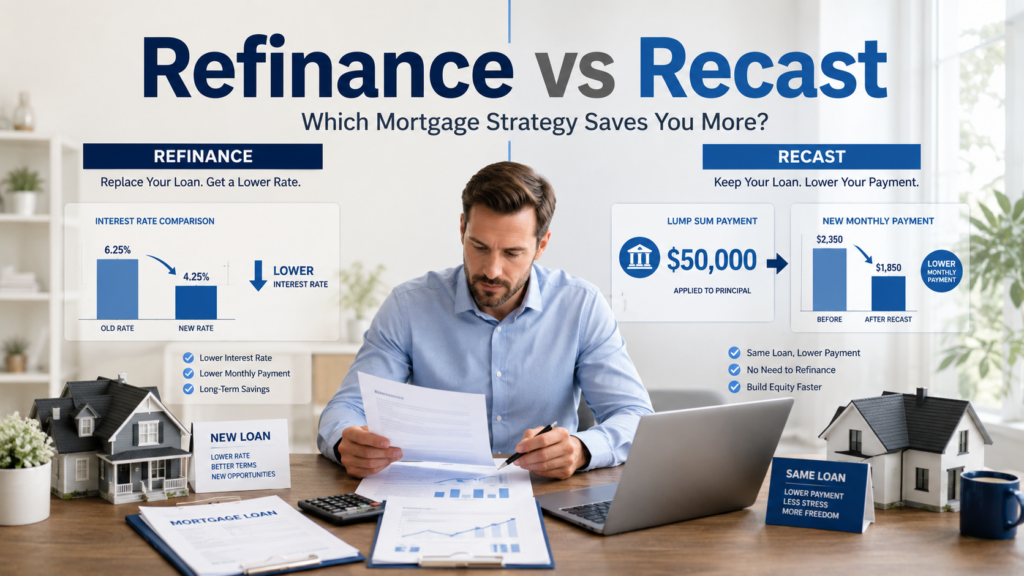
Mortgage refinancing is one of the most powerful financial tools available to homeowners — but it is not always the right move. Done at the right time and for the right reasons, refinancing can lower your monthly payment, cut tens of thousands in total interest, or unlock home equity for major expenses. Done at the wrong time, it can extend your debt, increase your costs, and reset progress toward payoff. The decision is driven by the current interest rate environment, your creditworthiness, how much equity you have built, and how long you plan to stay in your home. Lenders such as Rocket Mortgage, Chase Bank, United Wholesale Mortgage, Better.com, and Navy Federal Credit Union each offer different refinancing products, and the right choice depends on your specific goals. This guide explains what mortgage refinancing is, how the underwriting process works, the main types of refinance loans available, step-by-step how to refinance, common mistakes to avoid, and how to decide whether refinancing makes sense for your situation right now. What Is Mortgage Refinancing? Mortgage refinancing is the process of replacing your existing home loan with a new mortgage — typically with different terms, a new lender, or both. It helps homeowners reduce their interest rate, adjust their loan term, lower monthly payments, or access their home equity through equity withdrawal. The main purpose is to improve the financial terms of your existing mortgage based on changes in your financial profile or the broader interest rate environment. When you refinance, your new lender pays off your original mortgage and issues a replacement loan. You restart the amortization schedule on the new loan, which affects both your payment structure and your total interest cost over time. Types of Mortgage Refinancing Rate-and-Term Refinance The most common type of refinancing. You replace your current loan with a new one at a lower interest rate, a different loan term, or both — without changing the principal balance significantly. The primary goal is to reduce monthly payments or cut total interest paid over the life of the loan. Cash-Out Refinance A cash-out refinance replaces your existing mortgage with a larger loan and pays you the difference in cash. For example, if your home is worth $400,000 and you owe $250,000, you might refinance for $300,000 and receive $50,000 in cash. This is a form of equity withdrawal that converts home equity into liquid funds for renovations, debt consolidation, education, or other needs. Fannie Mae and Freddie Mac generally allow cash-out refinances up to 80% of the home’s appraised value for conventional loans. FHA and VA programs have their own equity withdrawal limits and eligibility requirements. Cash-In Refinance The opposite of a cash-out refinance. You bring cash to the closing table to pay down your principal balance — reducing the new loan amount and potentially qualifying for a better interest rate or eliminating private mortgage insurance (PMI). Streamline Refinance (FHA and VA) The Federal Housing Administration and the Department of Veterans Affairs offer streamline refinance programs that simplify the underwriting process for existing FHA or VA loan holders. These programs typically require less documentation, may allow an appraisal waiver, and involve reduced underwriting process steps compared to conventional refinancing. The FHA Streamline requires a seasoning period of at least 210 days from the first payment date of the original loan, and you must have made at least six on-time payments. The VA Interest Rate Reduction Refinance Loan (IRRRL) has similar seasoning requirements. Details vary — verify current terms with your servicer or lender. No-Closing-Cost Refinance Some lenders — including Better.com and others — offer no-closing-cost refinancing options where upfront fees are rolled into the loan balance or offset by a slightly higher interest rate. This lowers the break-even timeline but increases total interest paid over the loan term. It may make sense for borrowers who plan to move or refinance again within a few years. How Mortgage Refinancing Works When you refinance, you go through a process similar to your original mortgage application. Your new lender evaluates your creditworthiness, income, employment, property value, and existing debts. Here is what happens at each stage: Application and Documentation You apply with a lender — Rocket Mortgage, United Wholesale Mortgage (through a broker), Chase Bank, Navy Federal Credit Union, or another provider — and submit financial documentation including recent pay stubs, W-2s or tax returns, bank statements, and your current mortgage statement. Credit Review and Creditworthiness Assessment The lender pulls your credit report and evaluates your credit score, payment history, and existing debt obligations. Conventional refinance lenders typically require a minimum credit score of 620 for rate-and-term refinancing. Cash-out refinances often require 640 or higher. VA and FHA streamline programs may be more flexible. Credit score requirements vary by lender and loan type. Home Appraisal Most refinance loans require an independent home appraisal to confirm the property’s current market value. The appraisal determines how much equity you have — which affects the loan-to-value (LTV) ratio and the terms available. Some programs, including Fannie Mae’s Desktop Underwriter and Freddie Mac’s Loan Product Advisor, may grant an appraisal waiver for eligible borrowers based on automated valuation data. Underwriting Process The lender’s underwriting process involves verifying all submitted information and confirming the loan meets program guidelines. The underwriter reviews your financial solvency, debt-to-income ratio, property details, and title insurance documentation. This stage typically takes 2 to 6 weeks, depending on the lender and loan complexity. Closing and Escrow Account Setup At closing, you sign the new loan documents, pay any applicable closing costs (or roll them into the loan), and the lender funds the new mortgage. Your new lender pays off the old loan. An escrow account is typically established or transferred to collect property taxes and homeowners insurance going forward. There is a 3-day right of rescission for most refinances on a primary residence, during which you can cancel without penalty. This does not apply to purchases or investment property refinances. How to Refinance Your Mortgage: Step by Step Define your refinancing
 Skip to content